Sudhir Kumar, with over 30 years of business acumen in the domains of Management and Consulting in the UAE market is the primary resource behind the successful positioning of Kreston Menon as one of the leading Superbrand in the region. He works closely with all the market segments including Government, Corporate Sector, Free Zones as well as Financial Institutions. He spearheads the CSR initiatives of the organization along with his branding and corporate communication responsibilities.
Investing in the Middle East: Economic outlook for 2023/4
October 19, 2023
The Middle East economy is still attracting inward investment in 2023, despite a slowing global economy. The IMF and World bank are predicting GDP growth in the Middle East and North Africa (MENA) in 2023 to land somewhere between 2.4% and 3.1%.
Oil dependency and market dynamics
While oil and gas remain crucial for the Middle East’s economic landscape, especially for the Gulf Cooperation Council (GCC) states, there is a clear and evidenced interest in reducing this dependency by diversifying into other sectors to build more resilient, stable, and sustainable economies. Many regions have developed an ambitious tourism strategy, particularly Oman and United Arab Emirates (UAE), with Saudi Arabia’s flagship tourism investment opportunity NEOM picking up pace and The Line, Saudi’s planned 170km, $500 billion new city, due to be complete in 2039.
Diversification for economic stability
Oil and gas remain pivotal when investing in the Middle East. The EIU (Economist Intelligence Unit) notes that GCC states will particularly benefit from strong global demand and high prices for energy exports. The organisation expected oil prices to remain above $90 per barrel until at least mid-2023, echoing the International Monetary Fund’s (IMF) warning about rising oil prices due to global turbulence. (OPEC+) countries are unlikely to increase production despite pressure from the U.S. and Europe, focusing instead on price levels.
Inflation is another key concern, particularly for troubled states like Lebanon, Syria, Yemen, Iran, as well as Egypt and Turkey. According to the EIU, these countries are bracing for another year of double-digit annual consumer price inflation, with hyperinflation in Lebanon and Syria. This dovetails with the IMF’s report, highlighting inflation rates in some Middle Eastern countries.
Both the EIU and the IMF highlight the increasing focus of major Middle Eastern countries like Saudi Arabia, the UAE, and Iran on Asia for trade and investment. The EIU expects this “look East” policy to continue in 2023.
Promising tourism developments
Tourism is showing signs of recovery across the region, with the EIU anticipating international arrivals returning to pre-COVID levels by the end of 2023. This is due in part to major events like the FIFA World Cup in Qatar and efforts to promote tourism across Middle Eastern countries.
Business conditions in the GCC states are expected to be the most favourable in the region, per the EIU. These countries will see high oil and gas revenues spilling over into nonenergy sectors, helped by state-backed investments in diversification.
Challenges and opportunities investing in the Middle East
Both the World Bank and the EIU emphasise downside risks, including global shocks that could affect economic growth, stability, and social cohesion. Upside risks are limited and mostly hinge on external factors like a quick resolution of the war in Europe or stronger demand from China.
Ersel Barlak has 25 years of working experience in diversified roles such as corporate finance, business strategy, banking, audit and corporate business development covering a broad number of industries with significant project and deal execution leadership responsibility.
Ersel has a proven track record of leading projects such as valuations, project finance assignments, strategic assessments, market and financial feasibility studies, greenfield investments, portfolio reviews, competitive analysis, strategic planning, evaluation of investment targets, M&A engagements, formation of strategic partnerships, privatizations, divestitures, IPOs and SPOs.
Investing in Turkey: Can the economy find stability in 2024?
Investing in Turkey is a tale of two halves. As the 19th largest economy in the world, boasting a GDP of roughly $906 billion, Turkey is working against the odds to keep a seat at the economic table of the G20 powerhouses, navigating a complex list of setbacks, from natural disaster to hyperinflation.
The nation has experienced a notable journey of growth, reforms, and resilience over recent years. Ersel Barlak, partner at Kreston ATA, Turkey, examines Turkey’s foreign investment growth, second only to the United Arab Emirates in 2022. In the face of 58% inflation, Ersel discusses the firm’s trajectory amidst economic challenges and opportunities.
Overview of investing in Turkey
Turkey has witnessed ambitious reforms and high growth rates between 2006 and 2017, leading to a substantial reduction in poverty. The share of individuals below the $6.85 per day poverty line nearly halved to 9.8% between 2006 and 2020 according to World Bank data.
Ersel Barlak, with six years in the network under his belt, has a clear perspective on why that is.
“When compared to the EU countries, Turkey is the country with the highest youth population, half of Turkey’s population is under 32, which forms a youthful workforce with a strong potential,” shares Ersel, attributing part of the success to the nation’s intellectual capital.
“As of 2020, approximately 1 million undergraduates graduate from more than 200 universities yearly. The workforce in Turkey experiences the biggest growth among the EU countries as it becomes more and more productive every day .”
Despite the challenges of high private sector debt, persistent current account deficits, high inflation, and an unemployment rate double that of European G20 members, Turkey managed to achieve a robust economic growth of 5.6% in 2022 following the COVID pandemic recovery.
Foreign investment: Istanbul’s significance
The country took a blow in February 2023 in the form of devastating earthquakes, which inflicted physical damage in 11 provinces, accounting for 16.4% of Turkey’s population and 9.4% of its economy. The direct losses are estimated at $34.2 billion according to a World Bank report, but reconstruction of that figure could potentially double.
Ersel reflects on Istanbul’s resilience and emergence as a regional hub for foreign investors amidst these adversities. “Particularly Istanbul has become a strong attraction centre for foreign investors investing in Turkey,” notes Ersel, underscoring the city’s strategic significance and adaptability.
OECD economic outlook for investing in Turkey
The OECD Economic Outlook, June 2023, further details this situation, projecting a moderate economic growth of 3.6% in 2023, attributed to weaker exports, while domestic demand continues to fuel growth. This was still the best outlook in the G20.
The extensive damage caused by the earthquakes has indeed disrupted economic activity, yet the rapid initiation of reconstruction work is expected to largely offset this negative impact. The unemployment rate is anticipated to hover around 10%, and inflation, currently at 58%, is projected to “return to normal” rates of 15% by the end of 2025, with nominal wages experiencing a rapid ascent.
Investment incentives and strategic advantages
So what is bringing foreign investment to Turkish shores, despite uncertainty? Turkey offers a myriad of investment opportunities, bolstered by extensive incentive programs, a liberal investment environment, and strategic geographical leverage. “Hundreds of leading global companies in automotive, energy, and retail industries take advantage of competitive R&D incentives,” states Ersel. He further highlights Turkey’s role as a gateway for international companies aiming to expand into diverse markets and the youthful demographic profile that augments the nation’s appeal.
Focus, too, on uninterrupted reforms, makes the process of starting a business in Turkey appealing, Ersel believes, “Thanks to the reforms introduced in the fields of innovativeness of production, the sustainability of growth, qualified workforce, and collaboration in the international market, the average time period required to start a business shortened to 6.5 days from 38. In addition to its expanding domestic market, Turkey also offers access to approximately 1 billion consumers in the regional market with the support of free trade agreements .”
Investing in a greener future
Looking to the future, Kreston ATA is focusing on expanding its Corporate Finance & Advisory business. While acknowledging that the demand in specific service areas has remained constant, Ersel highlights the firm’s commitment to leveraging emerging opportunities and adapting to the evolving economic landscape. The integration of ESG policies is also gradually gaining traction in Turkey. “ESG is a new concept to our clients. Frankly speaking, it is not a priority on their agendas,” reveals Ersel.
However, he does predict a shift in this outlook, as clients exporting to the EU will need to comply with regulatory standards, hinting at potential future investment in this area to align with international business norms.
Conclusion
Turkey, with its blend of historical significance, economic resilience, and strategic advantages, remains a destination for foreign investment. As the nation navigates economic challenges and opportunities, insights from Ersel Barlak provide a glimpse into the evolving narrative of doing business in Turkey – a tale of adaptability, strategic foresight, and continuous growth.
18 October is World Ethics Day, a global observance that promotes ethical practices and principles across various domains. At Kreston Global, we wish to use this opportunity to celebrate the crucial role of ethics in accounting, tax, and auditing. In these professions, ethics is more than a guideline; it’s the bedrock of trust, transparency, and accountability. It reminds professionals to uphold the highest moral and professional standards, particularly in our complex and interconnected world.
What is the role of ethics in the accounting industry? Ethics is of the utmost importance in accountancy. We are one of only a few industries with a Code of Ethics that sets out how professional accountants in practice and business should behave and act. It’s the cornerstone of our profession, guiding us in doing the right thing, even when no one is watching or would even notice.
You recently shared the 2023 edition of the International Ethics Standards Board for Accountants (IESBA) Code of Ethics. Are there any noteworthy updates you would like to comment on?
Yes! The IESBA Code of Ethics is usually updated annually to keep it up to date with all the latest developments in the profession, including consequential and conforming amendments resulting from changes to auditing standards, etc.
This year’s update includes two key revisions relating to (a) the definition of engagement team and (b) group audits. The revisions deal with the independence and other implications of the changes made to the definition of “engagement team” in the Code to align with changes to the definition of the same term in the ISAs and ISQMs. The revisions also address the independence considerations in a group audit situation. Both changes are effective for audits with periods beginning on or after 15 December 2023.
Ethics is at the heart of what you do. Have you any advice for managing ethics globally?
Perspective is critical. Sometimes, we can all get so close and involved with an issue that it can be challenging to keep a perspective on our actions. Having someone available within a firm to provide an independent view and opinion is really helpful.
Building the right culture within a firm is also essential, as it fosters openness, trust and confidence that if an issue is raised, it will be dealt with appropriately and not swept under the carpet. The right culture has to be built top-down and permeates the whole organisation. Ethics should be integrated into everything we do as accountants.
What challenges do members of the accounting industry face in today’s global environment?
There is ever-growing commercial pressure on accountants, sometimes resulting in incentives to do the wrong thing. Standing up for what is right can be incredibly difficult, sometimes to personal detriment, but it’s important that we do, as this encourages others to behave similarly. I’ve been in such situations, and it’s never easy, but the one thing we always carry with us is our reputation, and I treasure mine over and above any promotion, bonus or job prospect.
What are your key top tips for ethics in daily practice?
In a difficult situation, I always try to ask myself how my action (or inaction) would look to someone else. This is the core of the “reasonable and informed third party” concept, i.e. that even if something was technically not prohibited by the detailed rules, if a reasonable and informed third party would think it unethical, then you shouldn’t do it. It helps us not to try and bend the rules or look for loopholes; if it wouldn’t look right to a third party, we shouldn’t be doing it.
The best approach, though, is not to get into a tricky situation in the first place and thus avoid putting oneself into a situation which may result in an ethical dilemma. Avoiding temptation is much easier than resisting it!
Founded in 1998 by Ajibade Fashina and Albert Folorunsho, Pedabo will mark its 25th anniversary in November with a rebrand to Kreston Pedabo, part of a strategy to extend its international services offering to a wide range of private and listed companies. Made up of 10 partners and 150 staff across three locations in Nigeria, the firm specialises in audit, assurance, tax compliance and advisory, financial advisory and risk management, management consulting and other support services.
The addition of Pedabo to Kreston Global’s network further strengthens its African regional presence, which consists of 30 member firms across 29 countries providing a range of financial, audit and accounting, taxation and other advisory services to businesses exploring inbound and outbound growth opportunities.
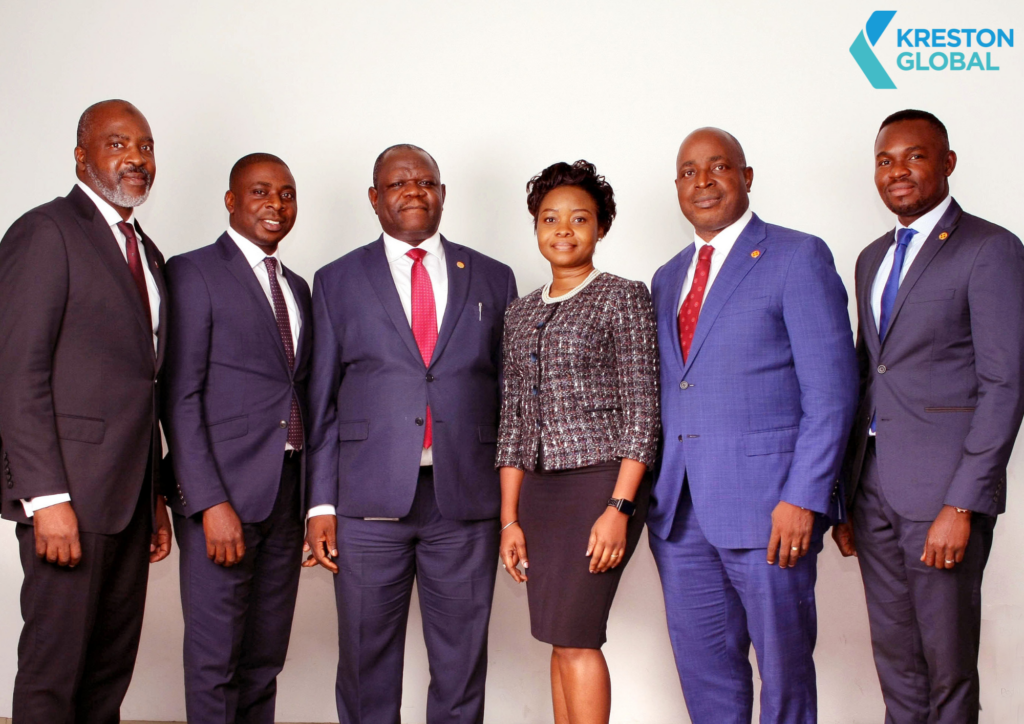
From left to right: Ajibade Fashina (Managing Partner), Kehinde Folorunsho (Tax Partner), Killian Khanoba (Snr. Tax Partner), Olubunmi Kuteyi (Tax Partner), Albert Folorunsho (Managing Consultant) and Peter Asemah (Audit Partner)
Liza Robbins, Chief Executive of Kreston Global, said:
“Pedabo has built an exceptional reputation in the Nigerian tax, audit and advisory landscape over the past 25 years. The breadth and depth of their expertise make them a trusted business partner for inbound and outbound clients. We look forward to working with them to build their standing in the international market, forging links across the network and beyond. They will be a great asset to our network and our African firms are extremely excited to be working with them.”
“Pedabo is indeed excited to begin this new phase; as founding partners, Albert and I are elated and proud of the progress that we have made in building the Pedabo we see today having truly established a Legacy of Excellence, but we are even more enthusiastic about the next 25 years and the new leadership that will take the firm to new heights with the Kreston brand. The choice of Kreston was not one that was made lightly, and we intend to establish a truly successful collaboration as we explore the Pedabo future leveraging the strengths and opportunities of the 13th largest accountancy network worldwide. So… Hearty cheers to Pedabo and on to the next 25 years of excellence on a global scale!”
Ajibade Fashina (Managing Partner), Albert Folorunsho (Tax Partner)
To learn more about doing business in Nigeria, click here.
News
Kreston Global announces ACCA certificate in sustainability for Finance Bursary Program
July 3, 2023
Kreston Global today announces a new partnership with the Association of Chartered Certified Accountants (ACCA) to provide subsidised bursaries to 40 member firms to undertake their Certificate in Sustainability for Finance.
ACCA’s Certificate in Sustainability for Finance course covers topics such as evaluating business value chains, models, and practices for sustainability; understanding climate change risks and financial implications; and explaining the UN SDGs and their significance for organizations. It also assesses ESG issues and information collection, analysis, and reporting processes, and emphasises the importance of sustainability analytics for organizations.
The new bursary partnership between Kreston Global and the ACCA is one pillar of Kreston’s Impact Strategy, established in 2022 to support the network in becoming more sustainable and to help member firms create ‘positive impact.’ It stands alongside a number of other sustainability initiatives including the launch of Kreston’s first Environmental, Social and Governance Advisory Committee, which is focused on helping firms begin their own journey to sustainability and carbon reduction, or – where they have already done so – helping them to accelerate their activities.
Liza Robbins, Chief Executive of Kreston Global, said:
“The finance and accountancy industry, as with many sectors, is undergoing an exciting period of transformation when it comes to ESG and sustainability. For our clients, as for ourselves, sustainability is not simply a buzzword but rather a critical aspect of responsible business practice that carries significant regulatory, reputational, and commercial weight. The ACCA has developed a number of initiatives internationally that we participate in – this partnership is a testimony to the value we place on our work together.”
“With investment decisions, contract tenders, and purchase behaviour increasingly filtered through ESG considerations, we are now seeing SMEs looking to stay ahead of the regulatory curve by incorporating sustainability reporting in line with the standards required of larger companies. Equipping our member firms with ESG analytical and advisory capabilities through ACCA’s Certificate in Sustainability for Finance is a significant opportunity to support our firms and our firms’ clients as they navigate to sustainable best practice. It also ensures that we, as a business network, continue to pursue our purpose of promoting positive impact around the world.”
Helen Brand, Chief Executive ACCA, said:
“At ACCA we’ve been working hard to help organisations across the world strive for a sustainable recovery from the pandemic, and meet the urgent challenges presented by climate change. Sustainability knowledge is increasingly crucial for finance professionals and organisations of all types, and we’re proud to have developed the Certificate in Sustainability for Finance to improve and widen this important skillset.
“We’re delighted to partner with Kreston Global in providing subsidised bursaries to help financial professionals and others take the certificate. Accountancy professionals play a crucial role in guiding organisations on adopting and reporting on sustainable practices to ensure long-term success, manage risks, and contribute to a more sustainable future. Undertaking this certificate will be an important step on the journey for many.”
News
A guide to starting a business in the Netherlands
June 28, 2023
Kreston Global firms in the Netherlands have recently expanded resources for entrepreneurs with its latest guide to starting a business in the Netherlands. This useful new guide offers practical insights and tips to facilitate a smooth transition into the Netherlands business landscape.
The guide provides a practical roadmap for entrepreneurs looking to establish a business in the Netherlands. It serves as an efficient tool, highlighting the most critical issues businesses might face when entering the Dutch market. However, the guide does not aim to be exhaustive, given the wide range of potential business scenarios and constraints.
Expert consultation from Kreston Global
To supplement the guide, Kreston Global encourages entrepreneurs to consult with their member firms located in the Netherlands for more detailed information. Whether it’s a question about the basics or a complex concern, the team is ready to provide expert advice.
Flexibility and liberal framework of Dutch law
According to Dutch law, a foreign individual or company can operate in the Netherlands through either an incorporated or unincorporated entity or branch. The guide elaborates on the flexible and liberal framework that Dutch corporate law provides for the organization of subsidiaries or branches.
The essentials of starting a business in the Netherlands
The guide offers a holistic approach to doing business in the Netherlands, covering a variety of key areas. These include starting a business, finding a location, understanding subsidies and financing, complying with tax legislation, managing personnel, and a list of useful addresses.
No matter where you are in your entrepreneurial journey, “Doing business in the Netherlands” is designed to equip you with the knowledge and resources you need to succeed. Backed by Kreston Global’s extensive network of eight member firms active in the Dutch region, this guide marks a significant step towards supporting global entrepreneurs in this internationally-focused and strategically positioned base for Europe.
If you are looking to expand your business into the Netherlands, read the doing business in the Netherlands guide. If you would like to speak to one of our firms in the Netherlands, please get in touch.
News
Ganesh Ramaswamy
Partner at Kreston Rangamani and Associates LLP, Global Tax Group Regional Director, Asia Pacific
Ganesh has extensive experience of more than 30 years in providing specialist tax services, particularly to large privately owned groups, with particular strengths in the property, retail, healthcare and hospitality industries. He has supported various entities with specialist advice on tax-effective structures and restructures, cross-border transactions on account of outbound and inbound India investments, mergers, acquisitions and divestments. Ganesh has also worked with stakeholders across businesses to deliver solutions such as tax due diligence, tax consolidation and restructuring of large family businesses in the Middle East, Asia, and Singapore.
ESG Reporting in Asia Pacific
May 1, 2023
Experts in our ESG committee comment on the progress of ESG in Asia Pacific, exploring the implications of new legislation and how it is changing doing business in the region.
Hong Kong and China
The ESG regulatory environment in Hong Kong and China is evolving rapidly, with new regulations being introduced all the time. This is due to a number of factors, including the growing importance of ESG issues for investors and consumers, the increasing pressure on companies to reduce their environmental and social impact, and the growing global consensus on the need to address climate change.
In Hong Kong, the SFC (Securities and Futures Commission) is the main regulator for ESG issues. In 2019, the SFC issued a circular on ESG funds, which set out its expectations for the disclosure of ESG-related information by fund managers. In 2020, the SFC launched a consultation on proposals to enhance climate-related disclosures by Hong Kong SFC-licensed fund managers. The SFC is also working with other regulators, such as the HKMA (Hong Kong Monetary Authority) and the HKEX (Hong Kong Exchanges and Clearing), to develop a more comprehensive ESG regulatory framework.
In China, the CSRC (China Securities Regulatory Commission) is the main regulator for ESG issues. The CSRC has issued a number of guidelines and regulations on ESG issues, including the Code of Corporate Governance for Listed Companies and the Standards for the Contents and Formats of Information Disclosure by Companies Making Public Offering of Securities. The CSRC is also working with other regulators, such as the Ministry of Finance and the Ministry of Environmental Protection, to develop a more comprehensive ESG regulatory framework.
The ESG regulatory environment in Hong Kong and China is still in its early stages of development. However, the pace of change is accelerating, and it is clear that ESG issues will become increasingly important in the years to come. Companies that are able to effectively manage ESG risks and opportunities will be well-positioned to succeed in the future.
Here are some of the key challenges and opportunities for companies operating in the ESG regulatory environment in Hong Kong and China: Challenges: • The regulatory landscape is complex and evolving rapidly, making it difficult for companies to keep up with the latest requirements. • There is a lack of clarity on some ESG issues, which can lead to uncertainty and compliance risk. • There is a risk of greenwashing, where companies make misleading ESG claims in order to improve their reputation. Opportunities: • There is a growing demand for ESG products and services, which provides companies with the opportunity to develop new products and services. • There is a growing awareness of ESG issues, which can help companies to better understand their ESG risks and opportunities. • There is a growing focus on ESG by regulators, which can help to improve the quality of ESG reporting and disclosures. Companies that are able to effectively manage ESG risks and opportunities will be well-positioned to succeed in the future.
At present, the clear ESG policy regulation mainly comes from the financial regulators, focusing on the mandatory specification of enterprise ESG information disclosure and the policy guidance of ESG investment, and due to the ESG contains E (environment), S (society), G (corporate governance) in different aspects of many issues, different government departments also have different emphasis on its regulatory function related issues.
Specifically, for different objects, the current ESG regulatory measures can be roughly divided into two categories: one is mandatory for listed companies or some specific enterprises, and is forced to disclose ESG information meeting the minimum standards through administrative regulations; the other has incentive requirements and encourages enterprises to disclose ESG information through market means such as green investment.
As the regulatory authority for the information disclosure of listed companies, China Securities Regulatory Commission (hereinafter referred to as CSRC) continuously studies and improves the ESG information disclosure system of listed companies and standardizes the operation of listed companies according to China’s national conditions and the stage of market development.
In terms of ESG investments, Domestic regulation focuses on green finance and inclusive finance, The introduction of a series of policy guidance, promotes commercial banks, public funds and other financial institutions to develop more green loans, green bonds, green funds, carbon financial products and other financial products based on ESG investment concept, Guide funds to favour clean, low-carbon and environmentally friendly enterprises and projects, “To provide appropriate and effective financial services to all social strata and groups requiring financial services at affordable costs (Notice of The State Council on the Issuance and Issuance of the Development Plan of Inclusive Finance (2016-2020))”, China will promote green and sustainable economic and social development.
Malaysia
In Malaysia ESG is also evolving rapidly, as the country strives to become a more sustainable and socially responsible nation. In recent years, there has been a growing focus on ESG issues by both the government and the private sector, and a number of new regulations have been introduced.
One of the most significant developments in the ESG regulatory environment in Malaysia has been the introduction of the Sustainable Development Goals (SDGs). The SDGs are a set of 17 global goals that aim to achieve a more sustainable and equitable future for all. The Malaysian government has committed to achieving all 17 SDGs by 2030, and has put in place a number of policies and initiatives to support this goal.
Another significant development has been the introduction of the Malaysian ESG Reporting Framework. The framework is designed to help businesses disclose their ESG performance and comply with relevant regulations. The framework is based on the Global Reporting Initiative (GRI) Standards, and covers a range of ESG issues, including climate change, water management, and human rights.
The ESG regulatory environment in Malaysia is still in its early stages of development, but the country is making significant progress. The government is committed to sustainability and social responsibility, and businesses are increasingly taking steps to comply with ESG regulations.
Here are some of the key ESG regulations in Malaysia: • The Sustainable Development Goals (SDGs): The SDGs are a set of 17 global goals that aim to achieve a more sustainable and equitable future for all. The Malaysian government has committed to achieving all 17 SDGs by 2030, and has put in place a number of policies and initiatives to support this goal. • The Malaysian ESG Reporting Framework: The framework is designed to help businesses disclose their ESG performance and comply with relevant regulations. The framework is based on the Global Reporting Initiative (GRI) Standards, and covers a range of ESG issues, including climate change, water management, and human rights. • The Companies Act 2016: The Companies Act 2016 requires companies to disclose their ESG performance in their annual reports. The Companies Act 2016 also requires a director of a company to exercise his powers in good faith in the best interest of the company. Bursa Malaysia has required Malaysian public-listed companies to include sustainability reporting in their annual reports. Directors of large, listed companies are also required to apply the corporate governance and sustainability practices in the Malaysian Code on Corporate Governance. • The Environmental Quality Act 1974: The Environmental Quality Act 1974 sets out the environmental standards that businesses must comply with. • The Occupational Safety and Health Act 1994: The Occupational Safety and Health Act 1994 sets out the safety and health standards that businesses must comply with. • The Labour Act 1955: The Labour Act 1955 and Employment (Amendment) Act 2022 sets out the employment standards that businesses must comply with. The ESG regulatory environment in Malaysia is evolving rapidly, and businesses need to stay up-to-date with the latest developments. By complying with ESG regulations, businesses can help to ensure a more sustainable and equitable future for Malaysia.
Australia
In Australia, the Australian Securities and Investments Commission (ASIC) has been a leading regulator in the ESG space. ASIC has issued a number of guidance documents and infringement notices on ESG issues, and has also undertaken a number of enforcement actions. In 2021, ASIC fined a major Australian bank $10 million for misleading investors about its ESG credentials.
Additionally, the Australian Accounting Standards Board (AASB) has been empowered to issue guidance on the accounting treatment of ESG-related items, including disclosures for climate related risk and sustainability reporting standards.
The New Zealand Financial Markets Authority (FMA) has also taken a number of steps to promote ESG investing in New Zealand. The FMA has issued a number of guidance documents on ESG issues, and has also undertaken a number of enforcement actions. In 2021, the FMA fined a major New Zealand bank $5 million for misleading investors about its ESG credentials.
Both ASIC and the FMA have made it clear that they will take action against companies that mislead investors about their ESG credentials. This has led to a number of changes in the way that companies report on their ESG performance. Companies are now more likely to provide detailed information about their ESG risks and opportunities, and to undergo independent ESG audits.
The growing regulatory focus on ESG issues is likely to continue in the years to come. As ESG investing becomes more mainstream, regulators are likely to take a more active role in ensuring that companies are complying with their ESG obligations. This will lead to a more transparent and accountable ESG market, which will benefit investors and companies alike.
In addition to the regulatory environment, there are a number of other factors that are driving the growth of ESG investing in Australia and New Zealand. These include: • The increasing awareness of climate change and other environmental issues • The growing demand for socially responsible investments • The increasing availability of ESG data and information • The growing sophistication of ESG investment products • The increasing evidence to suggest financial outperformance of companies that rate well on ESG metrics • The increasing pressure for companies to improve ESG performance as they otherwise face reputational and brand risk
The growth of ESG investing in Australia and New Zealand is likely to continue in the years to come. As more and more investors become aware of the importance of ESG issues, and as more and more ESG investment products become available, ESG investing is likely to become the norm.
If you have an ESG question for one of our experts in the Asia Pacific region, please get in touch.
News
Earth Day 2023: Liza Robbins
April 21, 2023
As Earth Day 2023 approaches, it is important to acknowledge the importance of sustainability in the corporate world. Due to the increasing environmental difficulties, it is crucial for businesses to integrate sustainable methodologies into their activities. In this article, Liza Robbins, Chief Executive of Kreston Global, provides her perspective on how tax and accounting specialists can assist businesses in focussing on sustainable practices.
Earth Day 2023 theme is ‘Invest in our planet.’ Businesses can profit significantly from a sustainable transition if they invest early on. How do you think businesses will profit – or benefit?
Climate change has become a crucial topic in today’s business world, with various stakeholders such as staff, clients, suppliers, and investors expressing their concerns about the impact of businesses on the environment. As a result, they have high expectations for companies to engage in sustainable practices. Ignoring these issues will result in negative consequences for the reputation and profitability of the business, as sustainable companies are more attractive to stakeholders.
The recruitment and retention of top talent have become significant challenges for businesses globally. Individuals increasingly seek to work for companies that have a positive impact on the planet, and the focus on sustainability can be a key factor in attracting and retaining employees. Therefore, organisations that integrate sustainable practices into their operations will benefit in terms of attracting and retaining talent.
Governments and regulators worldwide are also introducing new policies and laws to combat climate change, and organisations that adopt carbon reduction strategies now will be better equipped to navigate these new requirements. Adopting sustainable practices not only ensures regulatory compliance but also enhances the organisation’s reputation and brand value, positioning the organisation as a trailblazer in sustainability, which is highly attractive to stakeholders. In summary, businesses must recognise that sustainability is not a peripheral issue but a core concern that can drive long-term success and stakeholder satisfaction.
What is the role of accounting networks like Kreston Global in the education and behaviour change that firms and their clients need to take us to net zero by 2050?
At Kreston Global, we recognise the significant role we play in driving positive change in the world. As representatives of the accounting profession, we take great pride in our network’s ability to create a lasting positive impact. With over 25,000 individuals across 115+ countries, we have the reach and the influence to shape the global business landscape.
Our connectivity allows us to leverage our position to educate and consult on sustainable business practices, showcasing good practices that positively influence firms and their clients. At Kreston Global, we firmly believe that sustainability is a critical aspect of modern business, and we actively promote this mindset to our network and beyond.
Kreston Global recently partnered with Treedom Agroforestry to mitigate the emissions generated by enabling our members to connect face-to-face. What actions have you taken in your firms or your personal life that you can share that will help mitigate or reduce emissions?
At our organisation, sustainability is a top priority, and we have taken significant steps to integrate it into our operations. As part of our Strategic Plan, we have made a commitment to ESG and positive impact, and have enlisted the help of our network experts in this area, establishing an ESG Committee to identify best practice that can be shared across the organisation. We strongly believe that sustainability is not just a buzzword but a critical aspect of responsible business practices.
On a personal level, I am deeply committed to the Reduce, Reuse, Recycle mantra. I believe that we should all be mindful of our consumption patterns and strive to reuse items whenever possible. For instance, I have significantly reduced my car usage and prefer to walk or cycle for short journeys. I am delighted that the pleasant weather has made this more feasible lately.
At Kreston Global, we are also committed to reducing our carbon footprint. We carefully consider our travel plans and aim to combine multiple uses for a single flight whenever possible, such as attending meetings or conferences. We are dedicated to doing our part in creating a more sustainable future, both at work and in our personal lives.
To read more about the sustaiblity and ESG reporting in Kreston Global, click here.
News
Earth Day 2023: Mahendra Rustagi
As we approach Earth Day 2023, it’s essential to recognise the significance of sustainability in the business world. With the growing environmental challenges we face, it’s crucial for businesses to incorporate sustainable practices into their operations. In this article, Mahendra Rustagi, CEO of Kreston SNR, shares his insights on how businesses can incorporate sustainability into their financial reporting and tax compliance, the benefits of investing in sustainable initiatives, available tax incentives, and how tax and accounting professionals can help businesses quantify the benefits of sustainable practices.
Mahendra pointed out that Indians have a deep respect and commitment towards the Earth, evident in their tradition of worshipping it as Mother and seeking forgiveness before any construction work. This respect for the environment is something that businesses can learn from and apply to their operations.
The business world is among the most significant emitters of greenhouse gases and other pollutants. How can businesses incorporate sustainability into their financial reporting and tax compliance?
The business/industry is responsible to the extent of about 30% of Total Green House Gases (GHG). So they have a huge responsibility to care for their environment and society in a governed manner.
The efforts of businesses in this direction of sustainability should be incorporated by way of a report which we should form as an integral part of reporting. Like in India, the top 1000 listed companies have been mandated to disclose their data related to sustainability efforts through a report called BRSR (Business Responsibility and Sustainability Report) which is attached to and forms part of financial reporting. This can help to build trust with stakeholders and demonstrate a commitment to sustainability.
Earth Day 2023 theme is ‘Invest in our planet.’ Businesses can profit significantly from a sustainable transition if they invest early on. How do you think businesses will profit – or benefit?
Early investment in sustainability would mean improved energy efficiency, lesser water consumption and less waste reduction resulting in efficient operations and reduced operating costs. All this means higher profitability. Also, improved reputation and brand image and higher valuations, motivated team of employees, loyal customers etc, so one can say the business will benefit hugely in long run.
Businesses which are better on the ESG front can stay ahead of potential future regulations, avoid the financial and reputational risks associated with non-compliance and bring long-term economic benefits. Overall, investing in sustainability early not only benefits the environment but can also bring long-term economic benefits to businesses.
What are some tax incentives available for companies that implement sustainable initiatives, and how can businesses take advantage of them?
In India, the government has not yet started any income tax incentives for sustainable initiatives, however, the government is seriously considering and granting some income tax incentives for use of renewable energy and higher directions on some social spending. The Government of India has introduced a scheme called –Production Linked Incentives (PLI ) where huge incentives are provided to a certain class of environment-friendly products manufacturing linked to production. For example, Producers of Electrolysers are being given huge incentives to manufacture Electrolysers for the production of Green Hydrogen. Also, there are incentives for Green Sustainable Buildings and Energy Efficiency through the Bureau of Energy Efficiency (BEE).
Globally, there are several tax incentives available for companies that implement sustainable initiatives. These include tax credits for investments in renewable energy, tax deductions for expenditures related to environmental protection, and accelerated depreciation for certain environmentally friendly assets. Some countries also offer tax incentives for green buildings or for companies that reduce their carbon emissions. To take advantage of these incentives, businesses can consult with tax experts to identify the specific incentives that apply to their sustainable initiatives and ensure that they comply with the applicable regulations. They can also ensure that their financial reporting accurately reflects the impact of their sustainable initiatives, which can further demonstrate their commitment to sustainability and potentially attract socially responsible investors.
How can sustainable practices positively impact a company’s bottom line, and how can tax and accounting professionals help businesses quantify these benefits in their financial statements?
Implementing sustainable practices can positively impact a company’s bottom line in several ways. For instance, it can help reduce operating costs by improving energy and resource efficiency, optimising supply chains, and reducing waste. Sustainable practices can also increase revenue by improving customer loyalty, attracting socially responsible investors, and accessing new markets. Sustainable business practices lead to an enhanced reputation, being more attractive to staff and business partners who value environmentally sustainable practices, and attracting new customers who are seeking environmentally friendly products and services. Relationship between sustainability management practices and business financial measures as higher return on investment (ROI) and sales growth have already been proven.
Tax and accounting professionals can help businesses quantify these benefits in their financial statements by identifying the relevant tax incentives and credits available for sustainable initiatives, accurately reflecting the impact of sustainable practices on the company’s financial performance, and guiding compliance with applicable regulations.
Tax and Accounting professionals can also make the businesses understand the return on investment (ROI)on their sustainable Investments by quantifying the benefits through categorisation and a scoring model for each SDG component which would help them to make informed decisions about future investments in sustainability.
In conclusion, Mahendra’s insights inform us that businesses have a significant role to play in addressing environmental challenges, and they can do so by incorporating sustainability into their financial reporting and tax compliance. By investing in sustainable initiatives early on, businesses can not only benefit financially but also enhance their reputation and attract socially responsible investors. Tax and accounting professionals can assist businesses in identifying tax incentives, accurately reflecting the impact of sustainable practices on financial performance, and guiding compliance with regulations. As we celebrate Earth Day 2023, let us all take a moment to reflect on the impact of our actions on the planet and work towards a sustainable future.
News
Earth Day 2023: Ganesh Ramaswamy
As Earth Day 2023 approaches, it’s important to consider the role that businesses can play in promoting sustainability and combating climate change. Ganesh Ramaswamy, Partner at K Rangamani and Associates LLP, provides valuable insights into how businesses can incorporate sustainability into their financial reporting and tax compliance.
The business world is among the most significant emitters of greenhouse gases and other pollutants. How can businesses incorporate sustainability into their financial reporting and tax compliance?
In order to reach the Paris Climate goals businesses need sustainability reporting standards to measure their social and environmental impact more effectively. The business world expects the most significant innovations to happen soon in the corporate accounting and tax reporting standards due to the inclusion of ESG and sustainability reporting in financial statement reporting. Many businesses are embracing sustainability goals and seeking to reduce their carbon footprints. Most businesses have started sustainability reporting on a voluntary basis in their financial statements. ESG and sustainability reporting are part of the board agenda for many companies. To move forward the finance reporting function in businesses must be integrated with ESG and sustainability reporting. Moreover, the finance teams of businesses the world over should contribute to the process of setting standards in sustainability reporting.
Earth Day 2023 theme is ‘Invest in our planet.’ Businesses can profit significantly from a sustainable transition if they invest early on. How do you think businesses will profit – or benefit?
Investing in sustainable practices would definitely see businesses improving their ROI in the next decade. Building and growing a sustainable business has a lot of benefits like attracting a large pool of capital, building a stronger corporate brand, and promoting long-term growth which will definitely help the company and the investors benefit a lot. Individual and institutional investors are investing heavily in companies that proactively adopt ESG practices and have them integrated into the business strategy. Adoption of renewable energy like solar energy, wind energy and bioenergy automatically reduces costs.
Corporations that understand the importance of adapting to evolving socioeconomic and environmental conditions are better positioned to identify strategic opportunities and overcome competitive challenges. Proactive and integrated ESG policies can help companies gain a competitive advantage over other industry players. Employees generally care deeply about the companies they work for and the businesses they support, hence, they embrace values that are aligned towards social good, and environmental and social responsibility.
What are some tax incentives available for companies that implement sustainable initiatives, and how can businesses take advantage of them?
The tax incentives for businesses that implement sustainable initiatives are referred to as “green incentives” which comprise the following among various others:
Accelerated depreciation for investments in the sustainable energy sector.
Vehicle tax credit for electric motor vehicles
Grants for small businesses which take sustainable initiatives
Emission reduction credits which are encashable
Grants on salary payment to employees coming out of a green initiative.
These types of incentives can push many businesses would move in a more sustainable direction, or boost that allows these businesses to make the initial investment in green energy options or set up a new eco-friendly venture.
Sustainability reporting is a form of non-financial reporting that enables companies to convey their progress towards goals on various sustainability parameters, including environmental, social and governance metrics, and risks and impacts they may face. By disclosing the sustainability report, companies are able to communicate more transparently with the public about their business activities related to non-financial management and performance aspects. Though a number of different measurement and valuation methods exist, most of them are focused exclusively on ecological aspects, i.e. impact on climate, forest decline or water. Tax and accounting professionals can help businesses to quantify these benefits by valuing the following key dimensions for sustainable development:
Effects of economic activity on the environment e.g., resource use, pollutant discharges, waste.
Environmental services to the economy e.g., natural resources, sink functions, contributions to economic efficiency and employment.
Environmental services to society e.g., access to resources and amenities, contributions to health, living and working conditions
Effects of social variables on the environment e.g., demographic changes, consumption patterns, environmental education and information, institutional and legal frameworks.
Effects of social variables on the economy e.g., labour force, population and household structure, education and training, consumption levels, institutional and legal frameworks.
Effects of economic activity on society e.g., income levels, equity, employment.
What is the role of accounting networks like Kreston Global in the education and behaviour change that firms and their clients need to take us to net zero by 2050?
Networks like Kreston Global should act as strategic visionary which understands and guides the member firms on the trade-offs among people, the planet and profits. The networks can also function as a catalyst which can align the member firms’ strategy and culture so as to develop a sustainability agenda for the member firms. It is also quite easy for networks to provide an integrator role among member firms spread over various regions so as to uphold an overall commitment to the sustainability of the network.
Kreston Global recently partnered with Treedom Agroforestry to mitigate the emissions generated by enabling our members to connect face-to-face. What actions have you taken in your firms or your personal life that you can share that will help mitigate or reduce emissions?
The initiatives taken by our firm are the following:
Pooling of cars among staff while commuting to the office
Vegan food replaces fish and meat for lunch.
Water in glass bottles replaces PET bottles.
Use of natural light during daytime.
Focus on staff recreation facilities.
Increase in per diem for employees to travel by train instead of planes.
Floor carpets are made of natural fibre and not artificial fibre.
Employees are encouraged to use cotton clothing over synthetic clothing.
Natural jute bags replace plastic containers.
To conclude, Ganesh makes note of the importance of incorporating sustainability into financial reporting and tax compliance is a vital step for businesses in reducing their carbon footprint and achieving sustainability goals. Investing in sustainable practices benefits businesses in the long run, as it improves ROI, attracts capital, and strengthens the corporate brand. Tax incentives for implementing sustainable initiatives can help businesses to make the initial investment in green energy options or set up new eco-friendly ventures. On this Earth Day 2023, let’s pause and consider how our actions affect the planet and strive for a future that prioritises sustainability.
News
Earth Day 2023: Andrew Griggs
Earth Day is a global event celebrated every year on 22 April to raise awareness about the importance of protecting our planet and taking action against environmental challenges. As we approach Earth Day 2023, it’s important to consider the role that businesses can play in contributing to a more sustainable future.
Andrew Griggs, Senior Partner at Kreston Reeves and head of the Kreston Global ESG Advisory Committee shared his insights on how businesses can incorporate sustainability into their financial reporting and tax compliance, and how they can benefit from investing in sustainable practices.
1. The business world is among the most significant emitters of greenhouse gases and other pollutants. How can businesses incorporate sustainability into their financial reporting and tax compliance?
“I think there are great opportunities for UK businesses to incorporate sustainability into reporting, simply by looking at what is mandatory now for larger companies (over 500 employees) and following that lead to getting ahead of the curve as it will be mandatory for SMEs soon. From a financial management perspective, all business benefits from knowing their ESG risks and opportunities, and seeing what the impact of their business has on their wider community and stakeholders. And of course, it gives anyone looking closely at that business, be it as an investor, potential recruit or to do business with, a sense of the business culture, values and ethos.”
2. Earth Day 2023 theme is ‘Invest in our planet.’ Businesses can profit significantly from a sustainable transition if they invest early on. How do you think businesses will profit – or benefit?
“As I mentioned above, getting in early is always useful as it can take time to build a comprehensive ESG approach. I know from our own journey as a firm that wanted to have a positive impact on the world and society that the earlier you start the better. We began ours in 2018 and in March this year have achieved B Corporation certification which was one of our goals. The benefits of this inside-out approach have been substantial in terms of increasing staff engagement and morale, improving our financial performance, creating standout in the marketplace, and attracting/retaining clients.”
3. How can tax incentives for sustainable initiatives positively impact a company’s bottom line, and how can businesses take advantage of them with the help of tax and accounting professionals to quantify these benefits in their financial statements?
“Environmental tax incentives in the UK are quite good – there are capital allowances on energy efficient practices (improving heating and energy consumption) and investments in zero carbon technology (ie building infrastructure/electric car/bikes for staff etc). We know that adopting these and other measures such as turning down the heating slightly, going paperless, encouraging recycling and looking at lower water usage and plastic reduction has had a considerable impact in a positive way on our bottom line.”
4. What is the role of accounting networks like Kreston Global in the education and behaviour change that firms and their clients need to take us to net zero by 2050?
“In Kreston we have the opportunity to reach – both across our 165 member firms in 115 countries but in turn to influence and engage their clients and people. This allows us to change behaviours across a large global footprint and create impetus for change by galvanising the whole network. Our network’s impact strategy includes a committee of some of our ESG leaders to help direct and mentor other firms in this area.”
5. Kreston Global recently partnered with Treedom Agroforestry to mitigate the emissions generated by enabling our members to connect face-to-face. What actions have you taken in your firms or your personal life that you can share that will help mitigate or reduce emissions?
“As previously mentioned, as a firm we have committed to becoming a B Corporation so we can live our values of not only becoming net zero but ensuring a long-term commitment to staying net zero – and helping others to do so as well as part of being B corp.“
In conclusion, Andrew’s insights highlight the importance of incorporating sustainability into businesses’ financial reporting and tax compliance, investing in sustainable practices, taking advantage of available tax incentives, and the role of accounting networks in driving education and behaviour change. As we celebrate Earth Day 2023 with the theme of ‘Invest in our planet,’ it’s important to remember that businesses can profit significantly from a sustainable transition if they invest early on.
News
ESG reporting in North America
April 13, 2023
Experts in our ESG committee comment on the progress of ESG in North America, exploring the implications of new legislation and how it is changing doing business in the region.
ESG reporting in North America and Canada
The ESG regulatory environment in the USA and Canada is evolving rapidly, with both countries taking steps to increase transparency and accountability for ESG performance. In the USA, the Securities and Exchange Commission (SEC) has proposed new rules that would require public companies to disclose information about their ESG risks and opportunities. The rules are still under development, but they have the potential to significantly impact the way that ESG is managed by companies in the USA.
In Canada, the Canadian Securities Administrators (CSA) have also taken steps to increase ESG transparency. In 2021, the CSA published a guidance document on ESG disclosure for investment funds. The guidance document provides information on how investment funds should disclose their ESG risks and opportunities, and it is intended to help investors make informed decisions about their investments.
Both the SEC and CSA are taking a proactive approach to ESG regulation, and their efforts are likely to have a significant impact on the ESG landscape in the USA and Canada. The new rules and guidance documents are designed to increase transparency and accountability for ESG performance, and they will likely lead to more rigorous ESG reporting by companies. This will make it easier for investors to compare ESG performance across different companies, and it will help to ensure that companies are taking ESG seriously.
In addition to the SEC and CSA, there are a number of other government agencies that are taking an interest in ESG. For example, the US Department of Labor has issued guidance on how ESG factors should be considered in retirement plan investments. And the US Environmental Protection Agency has issued new rules that require companies to disclose information about their greenhouse gas emissions. The ESG regulatory environment in the USA and Canada is complex and evolving. But it is clear that both governments are taking ESG seriously, and they are taking steps to increase transparency and accountability for ESG performance. This is good news for investors, who will have more information to help them make informed decisions about their investments. And it is good news for companies, who will be under more pressure to take ESG seriously and to improve their ESG performance.
News
Accounting leaders discuss the advantages of joining a network
In a recent Accounting & Business magazine feature, leaders from Kreston Global offered their insights on the benefits and factors to consider when joining a network, such as a larger group or association. The article includes comments from Kreston Global’s CEO, Liza Robbins, Modern Mutumwa, managing partner at Kreston Zimbabwe, and Sudhir Kumar, senior partner at Kreston Menon in the UAE.
When considering whether to join a larger group, such as an association or network, many accountancy firms weigh the advantages of being an independent operator against the benefits of being part of a larger entity. Joining a larger group can provide opportunities for extending the reach and expanding the knowledge base, as well as staff development and professional bonds across borders.
In addition, these groups offer support through annual conferences and online events, knowledge sharing, and work referrals that can lead to revenue growth. However, it is important to actively invest time in building relationships with other group members for these benefits to accrue.
‘What I always say to firms is really think about what you’re trying to do. Don’t just say it’s the next stage of your development – boil it down. Broadly, if you’re a firm wanting to develop, you’re looking for resources – you may be looking for a technical person because you don’t employ one yourself – so you might be looking more towards the networks that have that sort of resource. Across the world, there’s a challenge with identifying and retaining staff. One of the things our firms are saying to us is that staff perceive an international link as very positive. They enjoy the interaction we can give them from being part of something bigger.’
Modern Mutumwa, managing partner at Kreston Zimbabwe in Harare, Zimbabwe
‘I wanted a brand I could rely on to be competitive in the local market. We have also seconded staff to Kreston Reeves in the UK. They learned new things and gained exposure to larger clients. Some were able to lead assignments, which strengthened their technical skills and opened them up to interact with staff from a global perspective.’
Sudhir Kumar, senior partner at Kreston Menon in the UAE
‘We are on the Forum of Firms list, which is recognition for us, for the quality of our work. Everyone is very happy that the organisation has changed culturally because Kreston talks to everyone, not only the top management. Everyone is part of Kreston.’
Over the past 15 years, the terms “network”, “association”, and “alliance” have become less interchangeable. “Network” now refers to practices that are members of the International Federation of Accountants (IFAC) Forum of Firms, meaning they comply with the International Standard on Quality Control (ISQC 1), International Standards on Audit, and the International Ethics Standards Board for Accountants’ code of conduct. This membership is important as many banks, governments, and not-for-profits will only work with auditors who are Forum members. Networks may also have stricter rules than associations regarding systems, processes, branding, and marketing. Some networks enforce a common brand, while others do not.
To learn more about joining the Kreston Global network, click here.
News
Carmen Cojocaru
Managing Partner at Kreston Romania
Carmen Cojocaru is a highly qualified professional with extensive experience in the fields of accounting, audit, tax, and business process outsourcing. Additionally, Carmen’s involvement with the ESG committee and Kreston Global highlights her commitment to promoting ethical business practices and fostering sustainable growth within the industry.
ESG reporting in the Middle East
Experts in our ESG committee comment on the progress of ESG in the Middle East, exploring the implications of new legislation and how it is changing doing business in the region.
ESG in the Middle East
ESG reporting is becoming increasingly important in the Middle East and North Africa, as investors and governments look for companies that are committed to sustainability. In this article, we will take a look at ESG reporting across the MENA, with a focus on Saudi Arabia, UAE, Turkey, Egypt, and Israel.
As stakeholders and investors seek greater transparency, the popularity of ESG is on the rise. According to Global Sustainable Investment Alliance 2020 biennial report, at the start of 2020, sustainable investment reached USD35.3 trillion for the five major markets United States, Canada, Japan, Australasia and Europe, a 15% increase in the past two years (2018-2020) and 55% increase in the past four years (2016-2020). This is expected to grow to $100 trillion by 2025.
The Middle East is not immune to this trend. Here are some ways that transparent, principles-driven businesses can benefit from this trend:
Increased investment: as investors seek out companies that align with their values, businesses that prioritize ESG principles may see an increase in investment. This can help companies grow and expand their operations.
Improved reputation: by prioritizing ESG principles, businesses can enhance their reputation among customers, employees, and the wider community. This can lead to increased loyalty and support from stakeholders.
Reduced risk: ESG principles can help companies identify and manage risks related to environmental, social, and governance issues. By addressing these issues proactively, businesses can reduce the risk of negative impacts on their operations.
Some of the world’s leading ESG investors are already active in the region. For example, BlackRock, the world’s largest asset manager, has committed to investing $500 billion in sustainable assets in the Middle East over the next five years. This growing interest in ESG is driving demand for ESG reporting from companies in the Middle East. However, the region is still lagging behind other parts of the world regarding ESG reporting.
ESG Reporting Gap in the Middle East
A recent study by PwC found that only 42% of companies in the Middle East have a standalone ESG report. This compares to 73% of companies in Europe and 69% of companies in North America. The study also found that companies in the Middle East are more likely to report on environmental factors than social or governance factors. This is likely due to the fact that environmental issues are more visible and measurable than social or governance issues. The report commented:
“Environmental issues are increasingly coming to the fore as governments in the region seek to transition from oil and gas. In the run-up to the COP26 Climate Change Conference in Glasgow, the United Arab Emirates committed to net-zero carbon emissions by 2050; Saudi Arabia and Bahrain also pledged to achieve net zero by 2060.“
“Social values, such as supporting communities, are also important for businesses in the region. This commitment was seen clearly during the pandemic when family businesses in the region actively championed initiatives to help their people, suppliers and local communities. According to the results of PWC’s Middle East Family Business Survey (2021), 84% of the region’s family businesses retained as many staff members as possible, 56% took action to support the local community and 45% provided financial support or loans to their employees.“
“Governance standards and codes are already adopted in the region and are increasingly an area of focus. A review in 2014 by the OECD highlighted that several countries in the region had issued governance codes and guidelines for banks, insurance companies, state-owned enterprises, securities companies, and small and medium-sized enterprises (SMEs). Central banks, capital market authorities and corporate governance institutes issue these guidelines and codes. As the ESG agenda advances in the Middle East, some banks in the region are beginning to screen their investment products and loan portfolios for climate impacts, illustrating how governance is in constant evolution in the region.”
Opportunities for Improving ESG Reporting in the Middle East
Despite the challenges, there are a number of opportunities for companies in the Middle East to improve their ESG reporting such as adopting international standards such as the Global Reporting Initiative (GRI) or the Sustainability Accounting Standards Board (SASB) to help provide a framework for companies to report on their ESG performance in a consistent and comparable way. Sustainability Disclosure Standards being issued by The International Sustainability Standards Board (ISSB), where it has issued two exposure drafts:
1. IFRS S1 – General Requirements for Disclosure of Sustainability-related Financial Information
2. IFRS S2 – Climate-related Disclosures
The standards will likely become effective starting January 2024 and are expected to be issued by the end of Q2 2023.
Another opportunity is to engage with investors and other stakeholders. Investors are increasingly looking for companies that are committed to sustainability. By engaging with investors, companies can better understand their expectations and develop ESG reporting that meets their needs-High-quality reporting is directly related to increased value for an entity’s stakeholders. Entities with strong ESG performance, for example, are often perceived as lower-risk investments, making them more appealing to investors.
Finally, companies can also use ESG reporting to attract and retain employees. Millennials and Generation Z are increasingly interested in working for companies that are committed to sustainability. By reporting on their ESG performance, companies can attract and retain top talent.
In conclusion, ESG reporting looks increasingly important in the Middle East. Companies in the region can improve their ESG reporting by adopting international standards, engaging with investors and other stakeholders, and using ESG reporting to attract and retain employees.
ESG reporting examples
Here are some specific examples of ESG reporting from companies in the Middle East:
Saudi Aramco, the world’s largest oil company, publishes an annual sustainability report that covers its environmental, social, and governance performance. Aramco unveiled a green initiative endorsing a circular carbon economy and commitment to plant 50 billion trees in the Middle East.
Emirates NBD, a leading bank in the UAE, publishes an annual sustainability report that covers its environmental, social, and governance performance.
FAB, UAE’s biggest bank is the first bank in the MENA markets to set ‘financed’ emission reduction targets for the oil and gas, power generation and aviation industries. FAB is focused on the Net Zero push and is expanding the scope of green financing apart from operational changes.
Turkish Airlines, a leading airline in Turkey, publishes an annual sustainability report that covers its environmental, social, and governance performance.
EgyptAir, a leading airline in Egypt, publishes an annual sustainability report that covers its environmental, social, and governance performance.
Israel Aerospace Industries, a leading defence company in Israel, publishes an annual sustainability report that covers its environmental, social, and governance performance.
The challenge is to eliminate energy poverty as well as to keep the goal of capping global warming at 1.5 degrees Celsius alive.
These are just a few examples of the many companies in the Middle East that are taking ESG reporting seriously. As the demand for ESG information continues to grow, we can expect to see even more companies in the region publishing ESG reports. It has to be mentioned that ESG reporting has been made mandatory for the Public Joint Stock Companies in the UAE. EY Carbon – a strategy to decarbonise businesses by developing a credible plan to achieve net zero – is highly focussed in the region.
Companies need to consider that ESG is supported by a generation that values its principles, and this factor makes the framework an increasingly sought-after component of modern business.
News
Carmen Cojocaru
Managing Partner at Kreston Romania
Carmen Cojocaru is a highly qualified professional with extensive experience in the fields of accounting, audit, tax, and business process outsourcing. Additionally, Carmen’s involvement with the ESG committee and Kreston Global highlights her commitment to promoting ethical business practices and fostering sustainable growth within the industry.
ESG Reporting in the EU
Carmen Cojcaru from our ESG committee looks at the progress of ESG reporting requirements in the EU (European Union), and explores the implications of new legislation on businesses operating in the region.
ESG in the EU
Sustainability reporting enables companies to convey their progress toward goals on various sustainability parameters, including ESG (environmental, social, and governance) metrics and risks and impacts. This non-financial reporting helps companies communicate both positive and negative implications of their actions on the environment, society, and economy and accordingly set priorities. With the new EU CSRD-Corporate Sustainability Reporting Directive, corporates must adopt new rules and include new regulatory frameworks into their business strategies. This decision will make the EU the world leader in sustainability reporting standards and will impact around 50,000 companies across the EU (up from 11,700 currently), so the potential is enormous.
What exactly does the news refer to?
It implies and affects: strategy and policies, non-financial KPIs, governance on sustainability issues, double materiality, risk assessment and management, and taxonomy; therefore, it impacts the reporting standards. In short, CSRD requires organizations to focus on the objectives related to sustainability issues and to report on progress, including both prospective and retrospective information in achieving them. The new sustainability reporting rules will apply gradually, starting in 2024. The biggest challenge regarding the matter is the vague information.
More details about the standards will be known in June 2023, when the first set of ESRS adopted by the European Commission is expected, followed by the second set in June 2024.
To whom do these new sustainability reporting rules apply?
The reporting requirements will apply to all large companies, all listed companies (except listed micro-enterprises) and non-EU companies with branches or subsidiaries in the EU above certain size thresholds.
Listed SMEs will have the option to use simpler, proportionate standards and the option to not apply the directive for 2 years after entry into force. The CSRD also specifies reporting requirements for listed SMEs.
Reporting timeline of ESG in the EU:
Public-interest entities with more than 500 employees from 1 January 2024 (the first report will be published in 2025);
Large companies (that exceed 2 of the size criteria: over 250 employees and/or EUR 40 million turnover and/or EUR 20 million total assets) from 1 January 2025 ( the first report being published in 2026) ;
Listed SMEs from 1 January 2026 (first reports in 2027, deferral to 2029 possible);
Non-EU companies with branches/subsidiaries in the EU from 1 January 2028 (first reports in 2029).
Reports will have to be subject to independent assurance, provided by auditors or other assurance service providers, initially it will be limited assurance.
The International Sustainability Standards Board (ISSB) is a new standard-setting board created by the IFRS foundation trustees to assist investors and other capital market participants with useful information about companies’ risks associated with their activities from the ESG perspective.
In 2023 they are expected to finalize the two exposure drafts published by ISSB; one setting out general sustainability disclosure requirements and the other on climate-related disclosure requirements.
“The CSRD requires the company’s statutory auditor, another auditor (according to Member State’s option) or an independent assurance services provider (IASP) (Member State’s option), to provide limited assurance on a company’s reported sustainability information. Member States should set out equivalent requirements for IASPs around quality, independence, and oversight in line with the Audit Directive.”
The International Audit and Assurance Standards Board (IAASB) is developing a standard for sustainability reporting assurance, which you can learn more about here.
In addition, the International Ethics Standards Board for Accountants (IESBA) is developing suitable globally-applicable ethics, and independence standards in support of transparent, relevant, and trustworthy sustainability reporting. Learn more about it here.
NFRD is still in force
Just a reminder that the rules introduced by the Non-Financial Reporting Directive ( NRFD), (applicable to large public-interest companies with more than 500 employees), are still in force until companies have to apply the new rules of the CSRD.
Herbert Chain is a highly experienced author is a financial expert with 40 years of experience in business, accounting, and audit, having served as a Senior Audit Partner at Deloitte. He holds certifications from the National Association of Corporate Directors and the Private Directors Association, with knowledge of private company governance and effective risk management. He has extensive knowledge in the financial services sector, including asset management and insurance, and experience with SPACs.
The increasing use and acceptance of crypto-assets have prompted many businesses and investors to reconsider their approach to financial reporting, specifically in the area of fair value accounting. As digital assets become more prevalent, they are changing the way financial holdings are viewed and managed, even though traditional assets such as cash, inventory, and equipment still play an important role in many businesses’ financial statements. Herb Chain, from CBIZ MHM, the Kreston Global US firm, explores the implications of the latest FASB guidance.
As a result, accounting for digital assets has become a critical issue for businesses, investors and other stakeholders, and external auditors. Until very recently, the only U.S. guidance came from the AICPA (American Institute of Certified Public Accountants) through a practice aid that provided nonauthoritative guidance on how to account for digital assets.
Current U.S. Guidance
Under current accounting principles generally accepted in the United States of America (US GAAP), cryptocurrencies are considered intangible assets and are accounted for using the impairment model. This means that they are initially recorded at cost and subsequently tested for impairment if events or circumstances suggest that their value may have declined. Subsequent increases in the carrying amount of the asset and reversal of an impairment loss are prohibited.
On the horizon
On December 15, 2021, in response to feedback received on its June 2021 Invitation to Comment, Agenda Prioritization, FASB added a project to its research agenda to explore accounting for and disclosure of a subset of exchange-traded digital assets and exchange-traded commodities. On February 1, 2023, the FASB Board directed the staff to draft a proposed Accounting Standards Update (ASU).
On March 23, 2023, FASB published a proposed ASU, which would add a new subtopic to the FASB Codification: Intangibles—Goodwill and Other—Crypto Assets (Subtopic 350-60), Accounting for and Disclosure of Crypto Assets, which is intended to improve the accounting for and disclosure of certain crypto assets. In its press release, FASB said it received feedback that the “accounting for crypto assets as indefinite-lived intangible assets, which is a cost-less-impairment model, does not provide investors with decision-useful information or reflect the underlying economics of those assets.” If adopted, the proposal will provide the first explicit accounting standard on crypto assets in U.S. GAAP.
The proposed standard – briefly
The amendments in the proposed ASU would require an entity to measure certain crypto assets at fair value each reporting period in the statement of financial position each reporting period and recognize changes in fair value in net income. The proposed amendments also would require that an entity provide enhanced disclosures for both annual and interim reporting periods, including presenting crypto assets separately from other intangible assets.
The amendments in the proposed ASU would apply to all entities holding crypto assets that meet all the following criteria:
Meet the definition of “intangible asset” as defined in the FASB Accounting Standards Codification Master Glossary
Do not provide the asset holder with enforceable rights to, or claims on, underlying goods, services, or other assets
Are created or reside on a distributed ledger based on blockchain technology
Are secured through cryptography
Are fungible
Are not created or issued by the reporting entity or its related parties.
The amendments in the proposed ASU would require a cumulative-effect adjustment to the opening balance of retained earnings (or other appropriate components of equity or net assets) as of the beginning of the annual reporting period in which an entity adopts the proposed amendments. Upon issuance of a final ASU, early adoption would be permitted in any interim or annual period for which an entity’s financial statements have not been issued (or made available for issuance) as of the beginning of the annual reporting period. FASB noted that the Board will determine the effective date after it considers stakeholder’s feedback. Comments are due by June 6, 2023.
It is important to note that the proposed guidance is not yet final and may be subject to change based on feedback from stakeholders. However, it provides insight into how the FASB views accounting for digital assets and may impact future accounting standards in the US relating to other types of digital assets.
Many countries outside of the United States have developed their own accounting standards for digital assets. For example, the UK’s Financial Reporting Council (FRC) has issued guidance on how to account for cryptocurrencies and tokens. The guidance suggests that cryptocurrencies should be accounted for as intangible assets, and tokens should be accounted for as financial instruments.
Under IFRS (International Financial Reporting Standards), digital assets are accounted for using IAS 38, which provides guidance on how to account for intangible assets. Like current US GAAP, IAS 38 requires that digital assets be initially recorded at cost and subsequently tested for impairment if events or circumstances suggest that their value may have declined.
However, IFRS also provides guidance on how to account for digital assets using the fair value model. IFRS 13 requires that entities measure the fair value of digital assets based on market prices, if available. If market prices are not available, entities must use other valuation techniques, such as discounted cash flows or comparable transactions.
Where do we go from here?
Accounting for crypto assets is a complex and rapidly evolving issue that requires careful consideration. The AICPA practice aid, professional accounting standards for other countries, and IFRS provide guidance on how to account for digital assets, while the FASB’s recent proposal offers insight into potential changes to US GAAP. It is important to stay current with developments in accounting standards and to carefully consider the implications of different accounting models for crypto and other digital assets.
If you have any questions on crypto-assets, please get in touch.
News
Kreston Global retains 13th position in global rankings
March 23, 2023
Kreston Global has maintained its 13th position in the International Accounting Bulletin world survey. Kreston Global continues to enjoy steady growth, with a 4% turnover increase in 2022.
The network has attracted a record number of new firms in recent years and US firm CBIZ MHM has contributed significantly to the growth with key strategic acquisitions, including New York–based Marks Paneth, helping to propel CBIZ MHM from 13th to 8th position in North America regional rankings.
Liza Robbins, Kreston Global Chief Executive commented,
“We are delighted to have retained our global position, although our focus continues to be on delivering real benefits to firms to help them grow and thrive, and less about global rankings.
The fast pace of development of Kreston Global led to a new strategic plan being unveiled in 2021, which embraces the network’s wider purpose-led approach. The new firms that have joined us over the last 12 months have only enhanced the strong ties that connect our firms to each other.
2023 looks set to be another strong year of member growth, with excellent firms interested in joining the network.”
If you are an ambitious, internationally-focused firm that is interested in joining Kreston Global as a member, you can fill out a form to apply to start your application.
News
Stuart Brown
Kreston Global ESG Committee member, Head of Technical and Compliance at Duncan & Toplis
Stuart is an FCA-qualified chartered accountant with more than ten years of practical accounting and audit experience.
He leads the technical developments for Duncan & Toplis. This covers audit, financial reporting and maintaining the quality of work.
He has recently been appointed to Duncan & Toplis’ operations board and has become a member of the ICAEW’s influential Ethics Advisory Committee. Stuart also sits on the Kreston Global ESG Committee.
ESG reporting in the UK
March 8, 2023
ESG reporting in the UK applies to entities that are classified as ‘large’ for reporting periods beginning on or after 1 April 2019, there has been a requirement to report on energy use and associated greenhouse gas emissions.
For accounting periods beginning on or after 6 April 2022 UK company law has mandated disclosure covering climate-related matters for certain entities. Disclosure must include a description of:
Governance arrangements for climate-related risk assessments and opportunities, including a description as to how an entity identifies such risks, how they assess them and their response.
How this risk assessment links to the overall risk management process.
The most significant risks identified and their impact on an entity.
How able to cope with the risks identified an entity is covering different scenarios.
Specific targets (including KPIs) used by an entity to manage identified risks and how the entity is performing against those risks.
Such disclosure is not required for all entities and has been introduced only for:
UK companies that have more than 500 employees and are either traded, banking or insurance companies.
UK companies listed on AIM with more than 500 employees.
Other UK companies that have more than 500 employees and a turnover of more than £500m.
LLPs that have more than 500 employees and a turnover of more than £500m.
In addition, in the UK, the listing rules mandated by the Financial Conduct Authority (FCA) require premium-listed and standard-listed companies to make disclosures under the TCFD (Task Force for Climate-related Financial Disclosure) framework. Further details on this can be found at https://www.fsb-tcfd.org/publications/.
Transition Plan Taskforce
2022 also saw the launch of the Transition Plan Taskforce (TPT). The aim of this group is to standardise the disclosure framework relating to the communication of the transition plans (to net zero) of UK private companies, to ensure that consistent, detailed, robust and credible plans are in place. Further details can be found at https://transitiontaskforce.net/.
Although mandatory disclosure of ESG-related matters is currently focused on the largest entities, entities of all sizes should feel encouraged to start to bring in ESG matters into their reporting and strategic decisions. All companies will benefit from being aware of the risks that they face from ESG matters and on the impact that their activities have on a wider stakeholder group.
If you would like to talk to one of our experts about your ESG reporting obligations in the UK, please get in touch.
Steve Gully is a highly experienced fiduciary and company director with over 20 years of experience in the international financial services industry. He has worked in companies that have undergone acquisition, acquisition of others and have been sold, demonstrating his adaptability and ability to cope with change. With a significant background working in an International Private Bank, Steve has developed detailed knowledge of the UK property markets for residential, commercial, agricultural, investment, and development projects.
Steve is also a proven leader with excellent people management skills, and strong commercial, technical, and solution-oriented skills. He has acted as a trusted advisor to a number of UHNW families and individuals and has held appointments as a board member on regulated financial services businesses, trading companies, and joint venture companies. His areas of expertise include Trust and Fiduciary Management, Wealth Management, Trust Law, Fiduciary Compliance, Family Office, Private Trust Companies, UHNWI/HNWI, Offshore structuring, Discretionary Management, Administration services, and Contentious Disputes.
Understanding the Non-Dom Regime and the 2023 UK Spring Budget
February 20, 2023
Understanding the non-dom regime is crucial to ensure you comply with the tax laws and avoid penalties. Kreston Global HNWI expert, Steve Gully, Director at Alex Picot Trust, discusses the non-dom regime, recent changes, and the impact of the 2023 UK Spring Budget on non-doms with eprivateclient. Read the full article here, or the summary below.
What is the Non-Dom Regime?
The non-dom regime is a tax system that applies to individuals who are not domiciled in the UK. Non-doms have to pay tax on their UK income and gains, but they are not taxed on their foreign income and gains if they do not bring them to the UK.
Non-Dom Remittance Basis
Non-doms can choose to pay tax on the remittance basis, which means they only pay tax on the income and gains they bring to the UK. This can be an advantage for non-doms who have significant income and gains outside the UK. However, they must pay an annual charge to use the remittance basis if they have been UK resident for more than seven years.
Recent Changes to the Non-Dom Regime
In 2017, the UK government introduced new rules that affect the non-dom regime. Under these rules, non-doms who have been resident in the UK for 15 out of the last 20 years must pay tax on their worldwide income and gains. In addition, non-doms who have a UK residential property in a company structure are also subject to inheritance tax.
Impact of the 2023 UK Spring Budget on Non-Doms
The 2023 UK Spring Budget introduced several changes that affect the non-dom regime. Firstly, the annual charge for non-doms who have been UK resident for more than seven years has increased from £30,000 to £60,000. Secondly, the threshold for paying tax on worldwide income and gains has been reduced from 15 out of the last 20 years to 10 out of the last 15 years. Thirdly, non-doms who have a UK residential property in a company structure will now be subject to capital gains tax when they sell the property.
Conclusion
Understanding the non-dom regime is crucial for individuals who are not domiciled in the UK. It is essential to comply with tax laws and avoid penalties. The recent changes introduced in the 2023 UK Spring Budget have significant implications for non-doms, and it is essential to seek professional advice to ensure you understand your tax obligations fully. Remember that the non-dom regime is complex, and the rules are continually changing, so it is crucial to keep up to date with the latest developments.
If you would like to speak to Steve Gully about any impact the changes in the Spring Budget have had on your investments, get in touch.
News
Ankur Jain named new Middle East Indirect Tax Director
December 19, 2022
Kreston’s Global Indirect Tax Group has welcomed a new regional director. Ankur Jain leads the indirect tax practice at MMJS, part of Kreston Menon, our member firm in the UAE.
In accepting the role Ankur Jain said:
“It is an honour to be appointed as the Middle East regional director of the Global Indirect Tax Group (GITG), particularly when Indirect Tax was introduced in many countries in the Middle East. In this fast and ever-changing tax landscape in the region, this opportunity brings a unique opportunity for me to share knowledge, build partnerships, work on referrals, and ultimately add value to our clients and Global Indirect Tax Group (GITG).”
Search
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept All”, you consent to the use of ALL the cookies. However, you may visit "Cookie Settings" to change your consent.
This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
Cookie
Duration
Description
cookielawinfo-checkbox-advertisement
1 year
Set by the GDPR Cookie Consent plugin, this cookie is used to record the user consent for the cookies in the "Advertisement" category .
cookielawinfo-checkbox-analytics
11 months
This cookie is set by the GDPR Cookie Consent plugin. It is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional
11 months
This cookie is set by the GDPR Cookie Consent plugin to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary
11 months
This cookie is set by the GDPR Cookie Consent plugin. It is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others
11 months
This cookie is set by the GDPR Cookie Consent plugin. It is used to store the user consent for the cookies in the category "Other".
cookielawinfo-checkbox-performance
11 months
This cookie is set by the GDPR Cookie Consent plugin. It is used to store the user consent for the cookies in the category "Performance".
CookieLawInfoConsent
1 year
Records the default button state of the corresponding category & the status of CCPA. It works only in coordination with the primary cookie.
device_id
10 years
Cookie used to maintain a local copy of the user's unique identifier.
viewed_cookie_policy
11 months
This cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not a user has consented to the use of cookies. It does not store any personal data.
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Cookie
Duration
Description
__cf_bm
30 minutes
This cookie, set by Cloudflare, is used to support Cloudflare Bot Management.
bcookie
1 year
LinkedIn sets this cookie from LinkedIn share buttons and ad tags to recognize browser ID.
bscookie
1 year
LinkedIn sets this cookie to store performed actions on the website.
currency
1 year
This cookie is used to store the currency preference of the user.
lang
session
LinkedIn sets this cookie to remember a user's language setting.
li_gc
6 months
Linkedin set this cookie for storing visitor's consent regarding using cookies for non-essential purposes.
lidc
1 day
LinkedIn sets the lidc cookie to facilitate data center selection.
UserMatchHistory
1 month
LinkedIn sets this cookie for LinkedIn Ads ID syncing.
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Cookie
Duration
Description
ac_enable_tracking
1 month
This cookie is set by Active Campaign to denote that traffic is enabled for the website.
device_view
1 month
This cookie is used for storing the visitor device display inorder to serve them with most suitable layout.
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Cookie
Duration
Description
__kla_id
2 years
Cookie set to track when someone clicks through a Klaviyo email to a website.
_ga
2 years
This cookie is installed by Google Analytics. It is used to calculate visitor, session and campaign data and it also keeps track of site usage for the site's analytics report. The cookie stores information anonymously and assigns a randomly generated number to identify unique visitors.
_ga_M0XVMQMRZ1
2 years
This cookie is installed by Google Analytics.
_gat_gtag_UA_188891991_1
1 minute
This cookie is set by Google and is used to distinguish users.
_gat_gtag_UA_7661078_5
1 minute
This cookie is set by Google and is used to distinguish users.
_gid
1 day
This cookie is installed by Google Analytics. It is used to store information on how visitors use a website and helps to create an analytics report on how the website is performing. The data collected includes the number of visitors, the source of visitors and the pages visited in an anonymous form.
AnalyticsSyncHistory
1 month
Linkedin set this cookie to store information about the time a sync took place with the lms_analytics cookie.
CONSENT
16 years 5 months 19 days 16 hours 12 minutes
These cookies are set via embedded YouTube videos. They register anonymous statistical data e.g. how many times the video is displayed and what settings are used for playback. No sensitive data is collected unless you log in to your Google account, in that case your choices are linked with your account, for example if you click “like” on a video.
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.