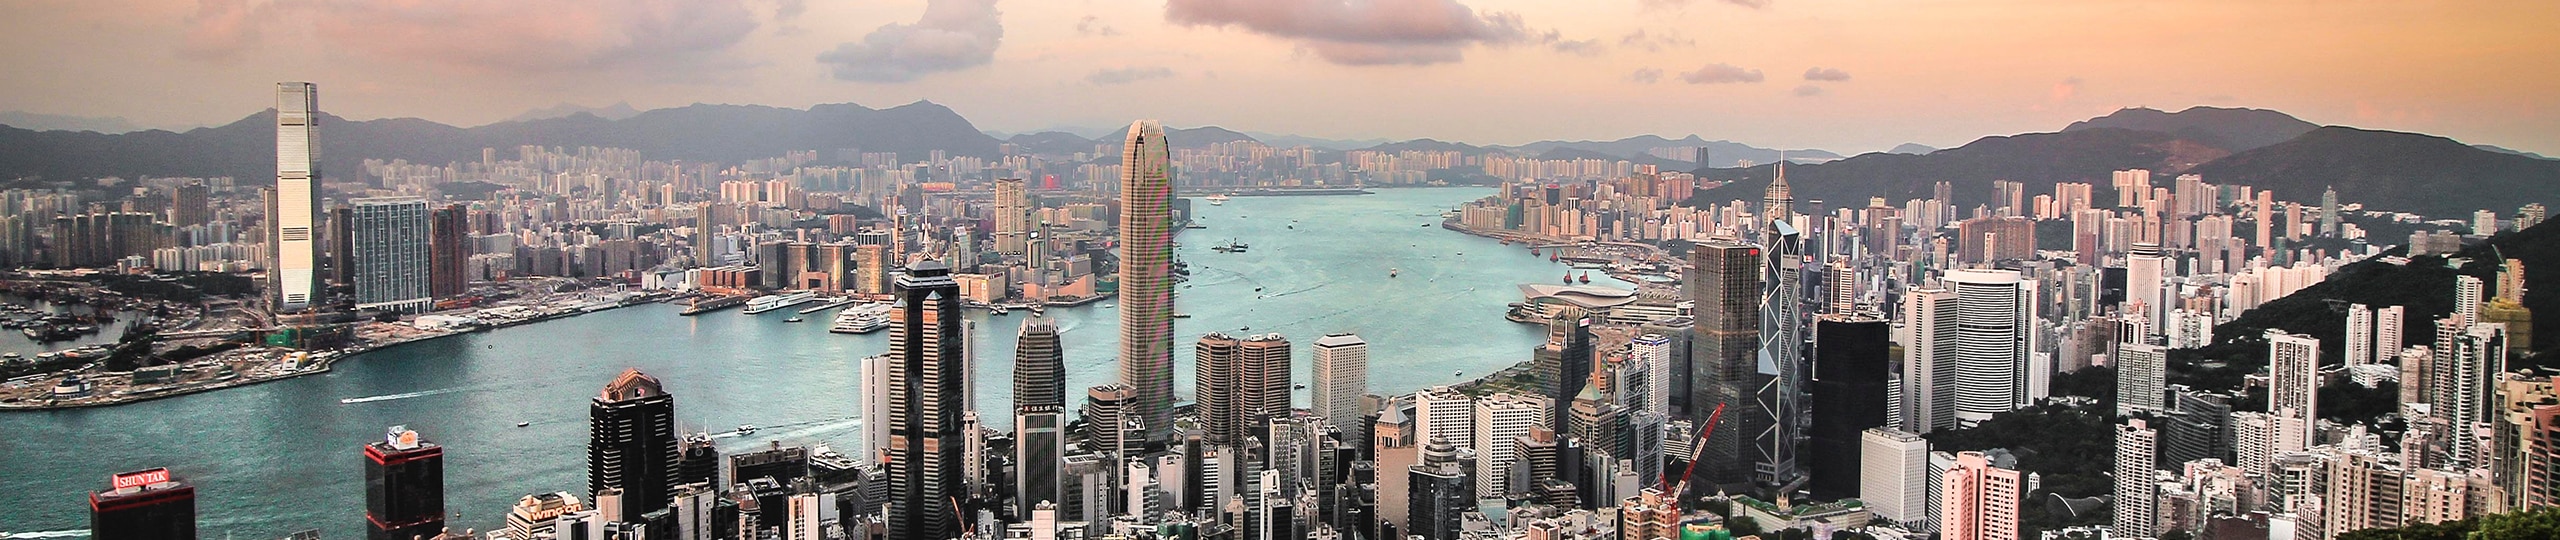
Doing business in Hong Kong
- How quickly can I set up a business?
- What is the minimum investment needed?
- How can I raise finance?
- What are the legal requirements for setting up my business?
- What structure should I consider?
- What advice can you give me in regards to payroll and taxation requirements?
- Is there anything else that I should know?
How quickly can I set up a business?
For a straightforward private company limited by shares, an electronic incorporation application is normally completed within one hour after the documents are submitted. A hard-copy application is normally completed within four working days.
What is the minimum investment needed?
There is no minimum capital or investment amount.
How can I raise finance?
You could raise finance from banks but normally they will ask for security for borrowings.
What are the legal requirements for setting up my business?
Most foreign investors register as a private limited liability company.
Formation procedures could be done either online via a direct application with the Companies Registry or by application using professional accountants or lawyers.
A minimum of one shareholder (native person or corporation) and director (native person) is required. No resident director is required.
Local company secretary and registered office is required.
What structure should I consider?
Private limited liability company would be the recommended approach.
What advice can you give me in regards to payroll and taxation requirements?
Any district in Hong Kong is available for foreign company investment.
Payroll and HR requirements:
Payroll is usually processed on a monthly basis. There is no monthly income tax deduction requirement for employers. The employer must report employees’ income annually, while employees report and pay their own tax annually.
There is a mandatory provident fund which both employer and employee each must contribute 5% of monthly salary with a top ceiling of HK$1,500 monthly.
Workmen compensation insurance is compulsory.
Tax/regulatory and reporting:
There is no value-added tax, sale tax, interest tax, dividend tax, capital gain tax and estate tax in Hong Kong
We have the following taxes:
- Corporation profits tax – standard tax rate is 16.5% with certain exceptions profits tax rate could be 8.25%, only annual tax reporting is required
- Individual income tax – If tax calculated using the progressive rates exceeds the amount calculated under the standard-rate method, the lower amount applies. From the 2024/25 year of assessment, the standard-rate calculation is two-tiered for higher incomes: 15% on the first HKD 5 million of net income and 16% on the remainder. Double tax relief is available. Only annual tax reporting is required.
- Property tax – flat rate of 15% on rental income, after a standard deduction of 20% allowance. Only annual tax reporting is required
- Stamp duty on transfers of Hong Kong stock – 0.1% of the consideration or value is generally charged on every sold contract note and 0.1% on every bought contract note, i.e. 0.2% in total for a normal sale-and-purchase transaction.
- Stamp duty on immovable property transactions – Buyer’s Stamp Duty and Special Stamp Duty no longer apply to residential property transactions executed on or after 28 February 2024. Ad valorem stamp duty continues to apply. Following the 2026-27 Budget measures, residential property transactions valued above HKD 100 million are subject to a maximum ad valorem rate of 6.5%, with lower-value transactions subject to the applicable progressive rates.
- Stamp duty on lease of immovable property – normally from 0.25% up to 1% of the yearly or average yearly rent.
Is there anything else that I should know?
A work permit is required for any foreigner who works in Hong Kong.
Our firms in Hong Kong
How can Kreston grow your business?
Select your business type:
Latest news
Kreston Brighture, February newsletter 2026
Read the latest financial news and updates in China from experts at Kreston Brighture.
Kreston Brighture, China, September newsletter 2025
Read the latest financial news and updates in China from experts at Kreston Brighture.
Cambodia’s new Transfer Pricing procedures for 2025
Kreston Cambodia’s written summary of the key takeaways of Cambodia’s new Transfer Pricing procedures for 2025.

